The alcoholic beverage market is booming as liquor manufacturers release new products and revamp old ones in order to increase sales at home drinking. The particular focus of this survey was premium beer, which is seeing many new releases.
First, comparing the changes in people's frequency of drinking alcohol with February 2020--before the pandemic--for all alcoholic beverages, more said it had decreased than said it had increased, but more said they were drinking at home more often (Figure 2). On the other hand, consumption at restaurants had declined significantly. Regarding their intended drinking frequency in the future, more people responded that they would like to drink more at restaurants than those that said they would like to do so more at home (Figure 3). Drinking at restaurants is predicted to gradually become more frequent.
Next, we focused on drinking at home, and looked at changes in drinking frequency by drink category. Among people who drank one or more days a week, beer came top, followed by malt-free and low-malt beer, then chuhai (Figure 4). On the other hand, looking at the differences in changes compared with before February 2020, low-alcohol and non-alcoholic beer saw double-digit increases (Figure 5). This is evidence of growth in the low-alcohol and non-alcoholic beer categories.
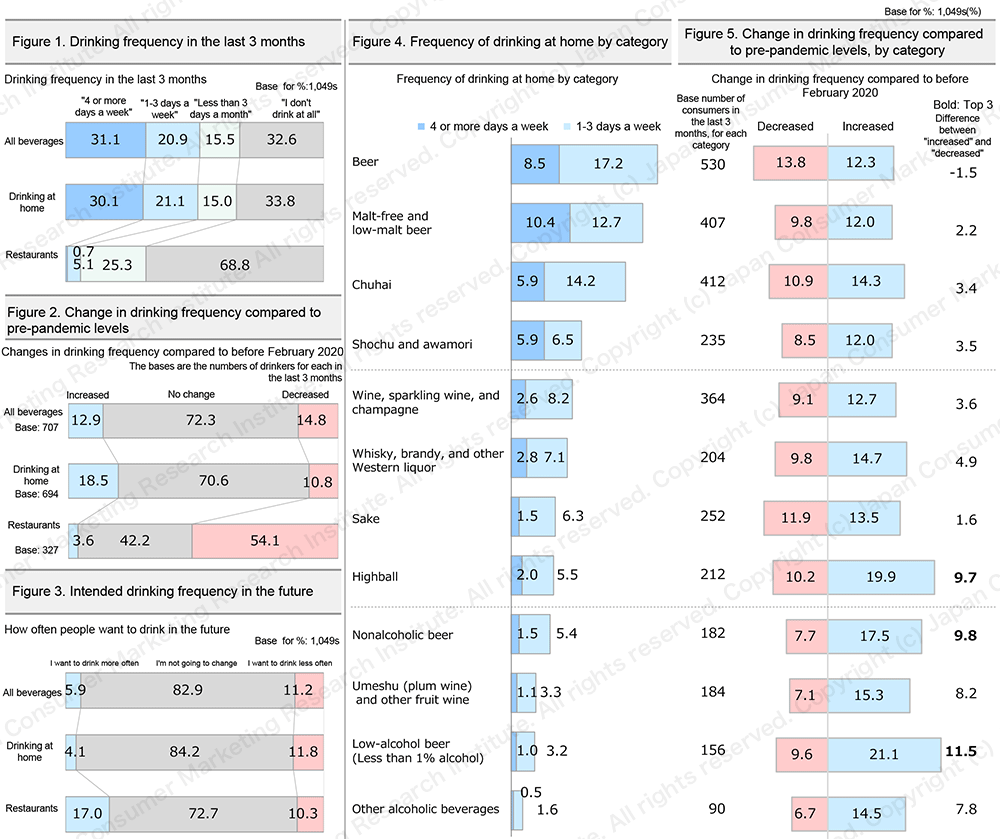
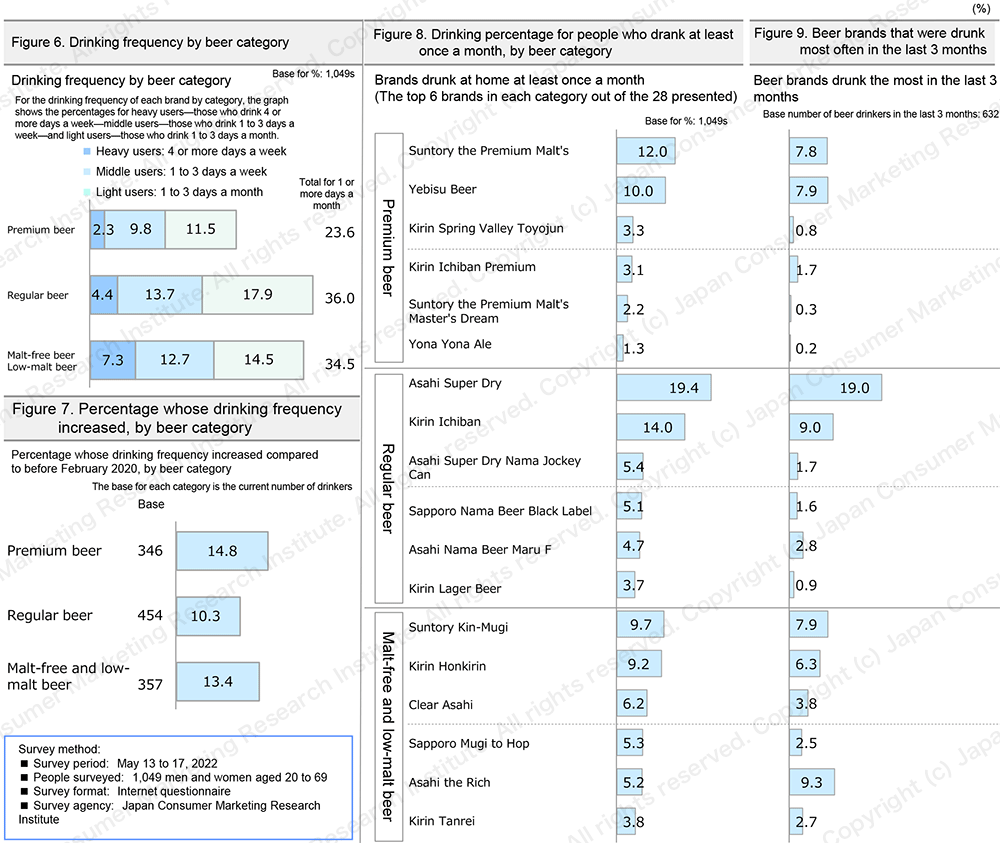
Looking at frequency of drinking at least once a week by beer category, 12.1% of them drank premium beer, about two-thirds of regular beer consumption (Figure 6). Furthermore, looking at the percentages for increased drinking frequency compared to before February 2020 by beer category, premium beer scored the highest at 14.8% (Figure 7). Regular beer, the most commonly consumed beer category, showed the lowest increase in frequency of consumption, while premium, malt-free, and low-malt beer showed higher increases.
Next, looking at the percentages for drinking at home at least once a month by brand, among the 28 listed brands, Asahi Super Dry had the highest rate at approximately 20%, followed by Kirin Ichiban (Figure 8). The premium beer Suntory the Premium Malt's came third, and Yebisu Beer fourth. Premium beers had the next highest drinking percentages after the two highest-scoring regular beers. Although they did not score as high as Asahi Nama Beer Maru F, which is said to have been a big hit last year, the premium beers introduced by each company came close to it despite the high price range, showing presence of premium beers in the beer market.
Also, among the brands that were drunk the most often in the last 3 months, about 20% of people who drank beer in that period answered "Asahi Super Dry," giving it the highest score (Figure 9). This shows how strong Asahi Super Dry's base is.
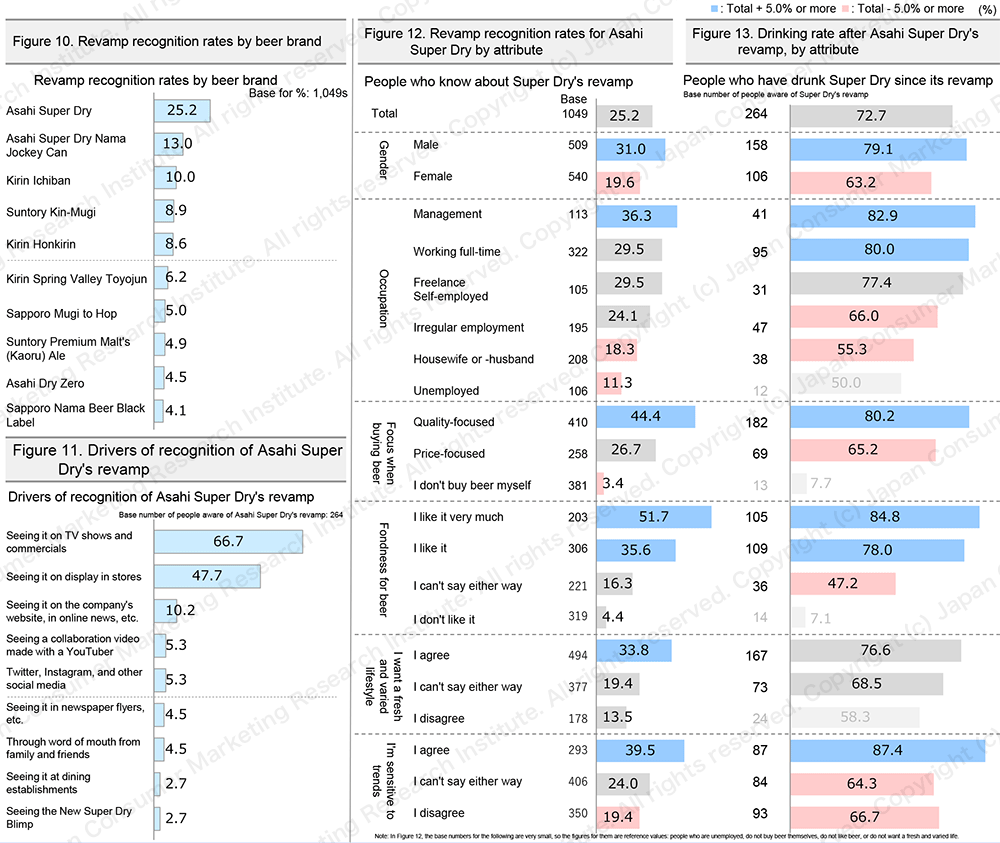
Looking at the awareness rates for recent beer revamps, Asahi Super Dry--which was revamped this February--had the highest score (Figure 10), with 1 out of 4 people aware of the revamp, including those who do not drink beer. TV shows, commercials, stores displays were the highest-scoring drivers of revamp awareness (Figure 11). The findings show that advertising and sales floor measures contribute greatly to awareness.
Next, looking at the drinking rates after Asahi Super Dry's revamp, the yield from recognition of it to drinking it among people recognize of the revamp is very high at 72.7%. This is about 18% of all respondents, including those who do not drink beer (Figures 12 and 13).
In addition, looking at the revamp recognition and post-revamp drinking rates for Asahi Super Dry by attribute, large differences can be seen based on gender and occupation. Awareness and drinking rates were high among men and people with managerial occupations. In addition, awareness and drinking rates were high among people who like beer, ones who are sensitive to trends, and ones who want a fresh and varied lifestyle. The findings show that 3 months after their revamped versions went on sale, what had initially been introductory segment beers were now being drunk as high-interest segment beers that were driving demand.
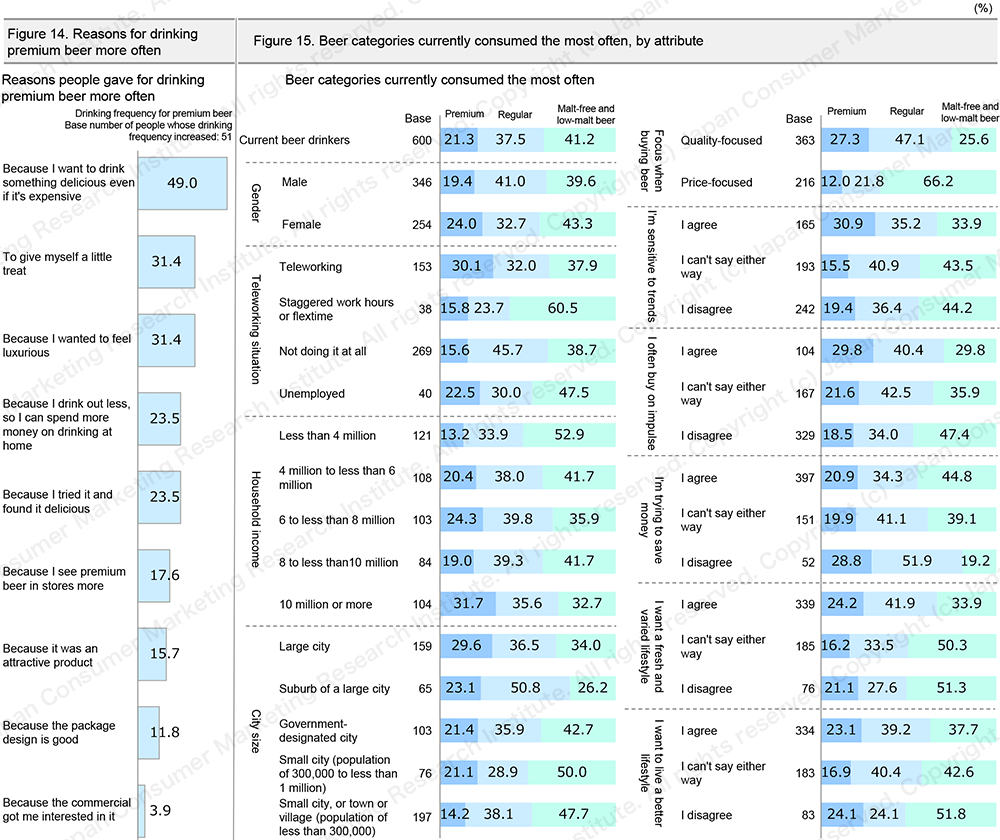
On the second page, the findings confirmed that people were drinking premium beer more often. Looking at the reasons, the most common one was "Because I want to drink something delicious even if it's expensive," accounting for about half of all respondents. This was followed by "To give myself a little treat" and "Because I wanted to feel luxurious" (Figure 14).
Looking at the beer categories currently consumed the most by various attributes, we can see differences in demand for premium beer between segments (Figure 15). In particular, there were large differences depending on basic attributes such as gender, teleworking situation, annual household income, and city size. Premium beer was mainly consumed by people who telework, have a high income, live in a large city, focus on quality when buying beer, or are sensitive to trends. The findings show that the demand for premium beer--the category companies are working on launching new products in--lies in the segments that are highly interested in beer. On the other hand, malt-free and low-malt beer were mainly consumed by people who have a low income, live in smaller cities, or want to save money.
As we have seen thus far, premium, malt-free, and low-malt beer are showing presence in the beer market, and the conventional structure centered on regular beer could increasingly split into an upper and lower price range.
Translating articles
- 6.9 Trillion Yen Market Created By Women― Will Afternoon Tea save the luxury hotels in the Tokyo Metropolitan Area
- Frozen Foods' Benefits Are Expanding, and Child-raising Women Are Driving Demand
おすすめ新着記事
消費者調査データ 緑茶飲料 首位「お~いお茶」、追う「綾鷹」、再購入意向には麦茶やブレンド茶も
無糖茶に関する調査結果をみると、お~いお茶が複数項目で首位だが、そのすぐ後ろに綾鷹が迫る結果に。茶飲料市場の最大ボリュームは緑茶飲料だが、再購入意向では麦茶やブレンド茶が高評価を得た。
消費者調査データ 炭酸飲料 「コカ・コーラ」首位は揺るがず、注目の"ギルティ炭酸"は?!
炭酸飲料の調査結果をみると、「コカ・コーラ」が盤石の強さをみせた。注目の新商品「ギルティ炭酸 NOPE」は広告接触などで上位に入ったが、ファンづくりはまだ途上の様子だ。
「食と生活」のマンスリー・ニュースレター 定着するワイヤレスイヤホン こだわり層に支えられる装着型オーディオ機器
装着型オーディオ機器の利用状況みると、動画・音楽の編集・制作や高負荷運動を行う人ほど利用率が高く、また動画・音楽の編集・制作や音楽にこだわりがある人ほど利用意向が高いことがわかった。